
Can You Be a Real Estate Agent AND a Mortgage Loan Officer?

Add Mortgage To The Mix
Aceable Mortgage's mobile-first pre-licensing course is the fastest way to add the second license without leaving your current career.
Quick Answer
- Yes: You can hold a real estate license and a mortgage loan originator (MLO) license at the same time, and in many cases you can work both roles on the same deal.
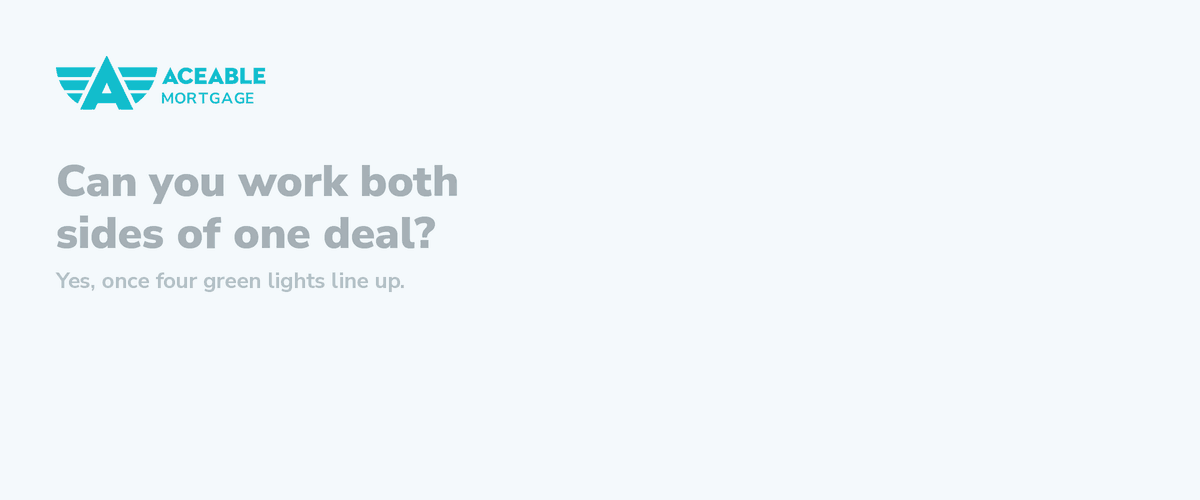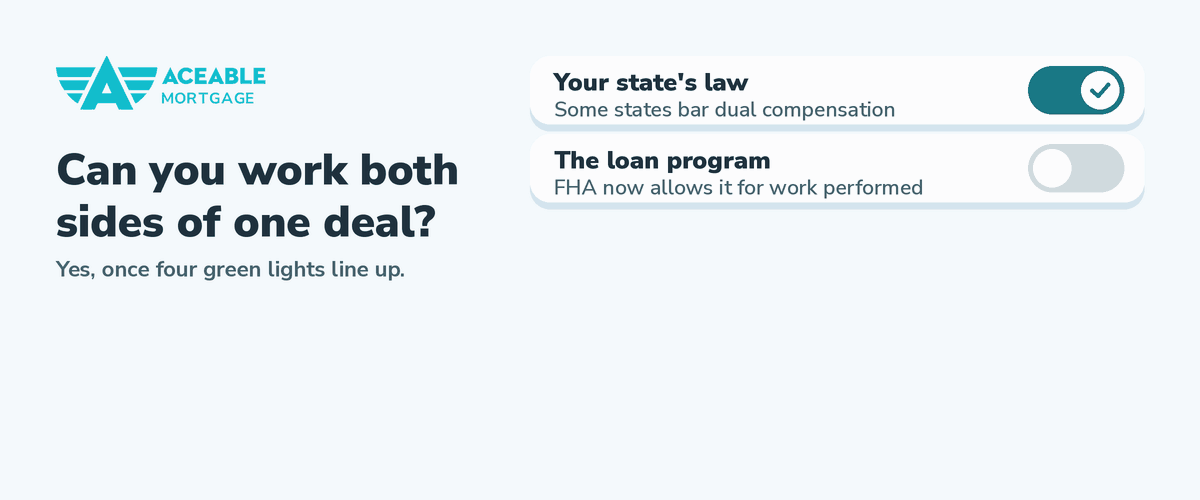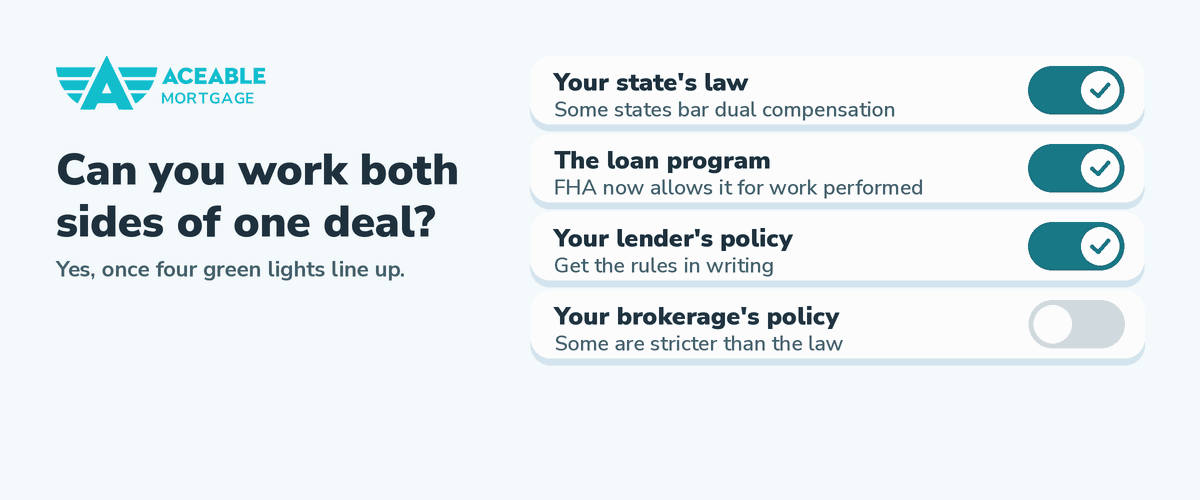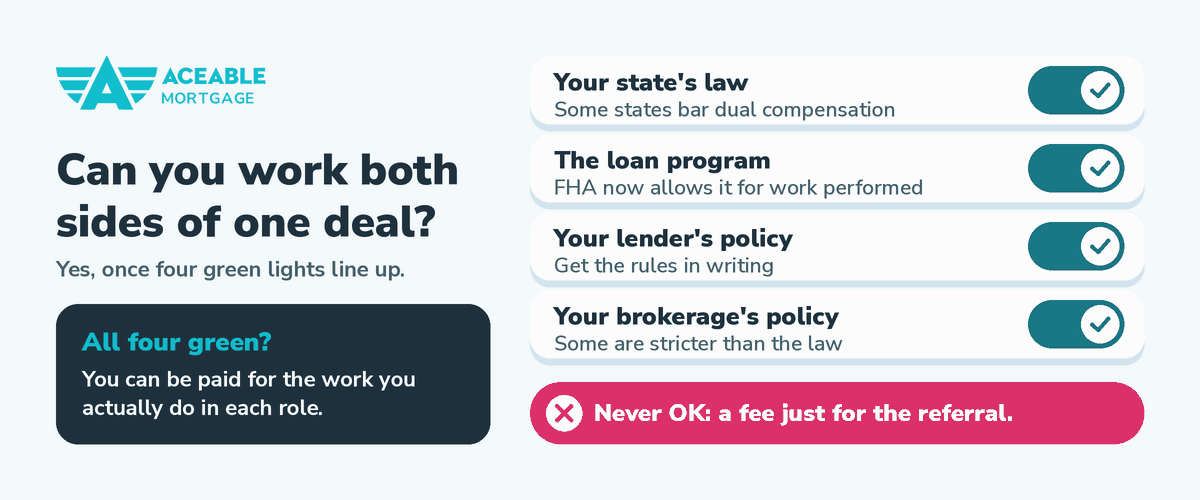
- Paid for work, never for referrals: Federal rules allow pay for services you actually perform in each role, but a fee for simply sending a client to a lender is off limits.
- Four sets of rules shape the details: Your state's laws, the loan program, your sponsoring lender's policy, and your brokerage's policy all decide how far you can take it.
Yes, you can be a real estate agent and a loan officer. Your real estate license comes from your state's real estate regulator, your MLO license comes from your state's mortgage regulator through the Nationwide Multistate Licensing System (NMLS), and federal law does not stop you from holding both.
The real question is what you can do with both licenses on a single transaction. That is where the rules live, and where most of the confusion lives too.
Not legal advice: This guide explains federal rules in plain language. Dual-role compensation is a compliance question, so confirm your setup with your state regulators, your sponsoring lender, and your broker before you take a deal in both roles.
What Can You Do as Both Agent and Loan Officer on the Same Deal?
You can be paid for real work in each role. Section 8 of the Real Estate Settlement Procedures Act (RESPA) prohibits kickbacks and referral feesRegulations 1024 14 Rules Policy but allows payment for services actually performed. HUD has said that when a real estate agent provides additional settlement services, those services are compensable only if they are actual2010 06 25 2010 15355 Real Estate Settlement Procedures Act Respa Home Warranty Companies Payments To Real Estate Brokers Documents, necessary, and distinct from the agent's primary work, and that a referral is never a compensable service.
FHA loans are in play now. FHA's Mortgagee Letter 2022-22Dfiles OCHCO Documents 2022 22hsgml.pdf Sites lets participants who do not have a direct impact on the mortgage approval decision hold multiple roles and sources of compensation for services actually performed, as long as the transaction follows all federal, state, and local rules. That reversed FHA's older ban on multiple roles in a single FHA transaction. People who directly affect approval, such as underwriters and appraisers, still cannot.
What Can't You Do?
- Take a referral fee: Accepting money from a lender or another loan officer for sending your buyer their way, without doing origination work, is exactly what RESPA Section 8 prohibits.
- Get paid twice for the same work: Each payment has to match a distinct service you actually performed.
- Steer the loan for a bigger paycheck: Federal loan originator rulesRegulations 1026 36 Rules Policy bar steering a borrower into a loan because it pays you more than another option would.
- Keep your dual role quiet: Tell your client about both roles in writing, up front. If your brokerage and mortgage company are affiliated, RESPA also requires an affiliated business disclosureRegulations 1024 15 Rules Policy when you refer between them.
What Do Most People Get Wrong?
Two myths, pointing in opposite directions. One says holding both licenses is illegal. It is not. The other says a dual license means every deal can run both ways. It does not, because your state, your loan program, your lender, and your brokerage each get a vote.
Many lenders and brokerages write their own dual-role policies, and some are stricter than the law. Get your sponsor's policy in writing before you tell clients you do both.
Where Do Dual-Role Rules Change by State?
States can go further than federal law. Some states still prohibit dual compensationNews Wake Nar Settlement Dual Licensing Carries Respa Steering Risks Nationalmortgageprofessional.com for dually licensed professionals, even where FHA allows it. Others layer on their own disclosure requirements, and your real estate commission may have separate rules about compensation tied to a client's financing.
How Do You Check the Rules in Your State?
- Read your real estate commission's rules. Look for sections on compensation, disclosure, and conflicts of interest.
- Check your mortgage regulator's requirements. The NMLS state checklistsSlr SitePages Checklist Compiler.aspx Mortgage.nationwidelicensingsystem.org point you to each state's licensing rules.
- Get both company policies in writing. Ask your sponsoring lender and your brokerage for their dual-role policies.
- Confirm the loan program on every deal. FHA, conventional, and other programs do not all treat dual roles the same way.
Choose a State and Course

Own The Closing Table
AceableAgent's mobile-first real estate prelicensing pairs naturally with your mortgage path, so you can earn on the home AND the loan.
How Does a Real Estate Agent Add an MLO License?
Your real estate license does not shorten the MLO path, but the path is clear and very doable. Here are the steps:
- Create your NMLS account. This gives you the NMLS ID that follows you through your mortgage career.
- Complete 20 hours of pre-licensing education. The federal minimum covers 3 hours of federal law, 3 hours of ethics, 2 hours of nontraditional lending, and 12 hours of electives, many states add their own hours, and it must be done before you apply.
- Pass the SAFE MLO Test. It has 120 questions (115 scored), a 190-minute time limit, and a 75% passing score. You can test at a Prometric test center or through online proctoring.
- File your MU4 and clear background checks. You submit the individual application in NMLS, provide fingerprints for an FBI background check, and authorize a credit report.
- Get sponsored. Your MLO license needs a sponsoring company licensed for mortgage business in your state. A real estate brokerage can sponsor you only if it holds that mortgage license too.
Where Aceable Mortgage fits: As an NMLS-approved provider (#1400102), we offer the 20-hour course as a live webinar, with 3-day daytime and 6-day evening sessions, or as an online instructor-led course completed within a 12-day window. Both are taught by instructors with real mortgage experience. Curious how hard the test is? Here is our honest take on NMLS exam difficulty.
How Long Does It Take to Add an MLO License?
- Fastest: About 3 to 5 weeks, if you take a short-format course, test soon after, and your state reviews quickly.
- Typical: About 1 to 3 months, depending on your study pace, test scheduling, background checks, and state review times.
Here is where the time goes:
- Education: 3 to 12 days, depending on course format
- Reporting: Up to 7 calendar days for your course completion to post to NMLS
- Study and test: Most people plan 1 to 3 weeks of prep before test day
- State review: Varies by state and application volume
For the full breakdown, see our MLO licensing timeline.
What Should You Budget For?
Fees vary by state and change over time, so pull current numbers from your state's NMLS checklist. Plan for:
- Education: Your 20-hour course, plus any state hours
- Testing: The SAFE MLO Test fee, charged per attempt
- Licensing: NMLS processing and state application fees
- Screening: Fingerprinting and your credit report
- Upkeep: Annual renewal and CE for both licenses once you are active
What Can Slow Down Your MLO License?
- Waiting on education reporting: Providers have up to seven calendar days to report your course to NMLS.
- A failed test attempt: You wait 30 days after each of your first two failed attempts and 180 days after a third.
- Background or credit questions: Disclosures that need an explanation add review time.
- No sponsor lined up: Without a sponsoring company, your license cannot go active.
Is a Dual License Worth It?
For many agents, yes, as an addition to your real estate business, never a replacement for it. A second license lets you guide clients through financing, deepens your referral relationships, and adds an income stream tied to a different part of the transaction.
See how MLO commission actually works, why California agents are adding the license, and the key benefits for agents. Mixed up on job titles? Start with MLO vs. broker, then explore your career options.
What Dual License Pays
The Aceable Mortgage commission guide breaks down how holding both licenses changes your yearly income math.
Frequently Asked Questions About Dual Licensing
Do You Need Separate Continuing Education for Both Licenses?
Yes. Your MLO license requires at least 8 hours of NMLS-approved CE every year, and your real estate license has its own CE rules set by your state real estate regulator. Track and renew each one on its own schedule.
Can Your Real Estate Brokerage Sponsor Your MLO License?
Only if the brokerage is licensed for mortgage business in your state. Otherwise, a licensed mortgage company sponsors your MLO license.
Does a Real Estate License Shorten the MLO Requirements?
No. You complete the same 20 hours of pre-licensing education, pass the same SAFE MLO Test, and clear the same background and credit checks as any other candidate.
Can You Be Paid as Both Agent and Loan Officer on an FHA Loan?
Under FHA Mortgagee Letter 2022-22, participants without a direct impact on the approval decision may hold multiple compensated roles for services actually performed, as long as the deal complies with all federal, state, and local rules. State law or company policy can still say no.
Stack The Licenses
Aceable Mortgage's NMLS-approved pre-licensing course gets you licensed on the mortgage side in weeks, so you can add it to your real estate career or start fresh.